Financial Advisor
Showing posts with label NZDUSD. Show all posts

Bearish outlook in NZD/USD persists

The New Zealand dollar was hit from both sides late last week: a ratings downgrade from S&P and Fitch and a sell-off in global stock markets (NZD/USD being the most sensitive to "Risk on/Risk off" among the actively traded crosses).

The downgrade was not a surprise as the "Kiwi" had been on negative watch for some time and the immediate market response was muted. But in combination with a generally nervous tone in global markets, downside pressure looks likely to predominate over the next few weeks.

From a technical perspective my Bearish Outlook in NZD/USD persists and the expectation now is for a sell-off toward my next Target about the 0.7490 level, with longer term risk still toward my Medium Term Objective of 0.7080, over coming weeks. 

Post FOMC Risk Selloff Continues, Dollar Firm

Markets have clearly responded negatively to Fed's Operation Twist announcement overnight. Asian equities are broadly lower with Nikkei down -2% following the -2.5% fall in DOW. 10 Year yield dropped to record low of 1.875% while 30 year yield barely held above 3%. Crude oil broke 85 level and should be heading back to 75 .71 low set August. Dollar index jumped on risk aversions and breaches 78 level today so far. Commodity currencies are hardest hit on risk aversion as well as on respective reasons. Sterling is also pressured by expectation of more QE from BoE and hover around record low against yen. Euro, on the other hand, is relatively resilient so far and is holding above 1.35 again dollar even though it's vulnerable.

As expected, the Fed announced to extend the average maturity of its holdings of securities so as to stimulate the economic recovery and to help ensure inflation is consistent with the dual mandate over time. The operation twist that the Fed adopts is an active one. It involves selling $400B of Treasury securities with maturities of 3 years or less and simultaneous purchase of a similar amount of Treasuries in the 6-30 year remaining maturity range. The Fed funds rate was keep unchanged at 0-0.25%. 3 Fed presidents who voted against additional policy easing were Richard Fisher, Narayana Kocherlakota, and Charles Plosser.

Additional pressure is seen markets after China HSBC manufacturing PMI dropped to 49.4 in September as export and output declined. The index has been staying in contrationary territory for three consecutive months and suggests further mild contraction in near term. The news added additional weight on Aussie, where China is the country's biggest trading partner. New Zealand dollar saw some pressure after RBNZ governor Bollard said there are "significant global risks" and there is no "particular rush" to raise rates even though the bank still has expectation to tighten. Canadian dollar is pressured by anticipate that crude oil is heading back to below 80. Canadian Prime Minister Harper also warned yesterday that the BoC is "prepared to intervene if they thought there were movements in the currency that were contrary to the country's interests and not being driven by actual underlying fundamentals", that is, intervening in the markets to curb CAD strength.

Looking ahead, Eurozone PMIs will be a major focus in European session and is expected to show further deterioration in the economic outlook. Swiss ZEW and UK CBI industrial orders expectations will also be released. In US session, main focus will be on Canadian retail sales and US jobless claims.

New Zealand Dollar is one of the weakest currency this week and the break of 0.7962 support confirms resumption of the whole fall form 0.8842 high. Near term outlook will remain bearish as long as 0.8118 resistance holds and current fall should now target next key cluster support level at 100% projection of 0.8842 to 0.7962 from 0.8572 at 0.7692 and 50% retracement of 0.6560 to 0.8842 at 0.7701.


GBP/JPY Daily Outlook

Daily Pivots: (S1) 117.68; (P) 119.14; (R1) 119.93; 

GBP/JPY drops to as low as 118.35 so far and broke key support level of 118.81. There is no sign of bottoming yet and intraday bias remains on the downside for deeper decline. Sustained trading below 118.81 will target 161.8% projection of 130.83 to 123.29 from 127.31 at 115.11 in near term. On the upside, note that break of 122.26 resistance is needed to signal short term bottoming in the cross. Otherwise, outlook will remain cautiously bearish even in case of recovery.

In the bigger picture, focus remains on 118.81 support. Sustained trading below this level will confirm resumption of the long term down trend from 2007 high of 251.09 and should pave the way to 61.8% projection of 215.87 to 118.81 from 163.05 at 103.06, which is close to 100 psychological level. Meanwhile, strong rebound from the current level, followed by break of 140.02 resistance, will revive the case that consolidation from 163.05 is merely the second leg of the consolidation pattern that started at 2009 low of 118.81. In such case, there should be one more medium term rise before the long term down trend resumes.

Economic Indicators Update

GMT Ccy Events Actual Consensus Previous Revised
22:45 NZD GDP Q/Q Q2 0.10% 0.50% 0.80%
7:00 EUR French PMI Manufacturing Sep P
48.5 49.1
7:00 EUR French PMI Services Sep P
54.2 56.8
7:30 EUR German PMI Manufacturing Sep P
50.2 50.9
7:30 EUR German PMI Services Sep P
50.6 51.1
8:00 EUR Eurozone PMI Manufacturing Sep P
48.6 49
8:00 EUR Eurozone PMI Services Sep P
51.1 51.5
9:00 EUR Eurozone Industrial New Orders M/M Jul
-1.20% -0.70%
9:00 CHF ZEW Survey (Expectations) Sep

-71.4
10:00 GBP CBI Trends Total Orders Sep
-5 1
12:30 CAD Retail Sales M/M Jul
-0.30% 0.70%
12:30 CAD Retail Sales Less Autos M/M Jul
0.20% -0.10%
12:30 USD Initial Jobless Claims
420K 428K
14:00 EUR Eurozone Consumer Confidence Sep P
-18 -16.5
14:00 USD Leading Indicators Aug
0.10% 0.50%
14:00 USD House Price Index M/M Jul
0.10% 0.90%
14:30 USD Natural Gas Storage

87B

Next Downside Levels for NZDUSD

The RBNZ was noncommittal on rates - touting domestic strength but expressing worries about the global economy. NZD dropped as risk appetite soured a bit in Asia. Today we look at possible downside targets for NZDUSD should key support give way.
 
The RBNZ's rate decision saw Bollard bemoaning the international economic risks, including the "real risk that global economic activity slows sharply."  He also expressed worry about the potential for a rising cost of bank funding. On the domestic front, the strength of recent data was noted and Mr. Bollard indicated that New Zealand didn't need rates as low as the current cash rate but that the balance of domestic/international factors demanded a pass for now. Forward rate expectations eased a couple of bps, but the market continues to expect that the RBNZ will be the only bank among the G-10 currency central banks that will raise interest rates in the coming year.
 
While the New Zealand economy has been strong and given the currency a boost, we have to consider a couple of factors here on whether it will remain resilient. First, the tremendously strong weakening impulse of late across Asian currencies versus the US dollar has to be giving the kiwi bulls some pause, as the market seems to be (justifiably) questioning the prospects for near to medium term Asian growth. A continuation of this trend will be difficult for kiwi traders to ignore. Secondly, the kiwi also got a tremendous boost from China's announcement of investments in New Zealand earlier this year. Whether this source of capital flows will continue is an open question, but it has already served to give "artificial support" relative to fundamental inputs like interest rate spreads as we show in the second chart below and further strength from these levels is certainly unwelcome from New Zealand's perspective.
 
Chart: NZDUSD
The technical situation for NZDUSD is very interesting here, as we are facing a somewhat sloppy, but still relatively well defined head and shoulders formation with a neckline fast approaching, or already almost here depending on how the line is drawn between the mismatching points on the chart. Still, we seem to be in a pivot zone just below current levels at 0.8115. The next targets lower are the 200-day moving average currently around 0.7930 and then the bigger area lower is all the way down at 0.7340. Of course, to see this latter level come into play, we would likely either need further turmoil in Asia markets and/or the S&P500, for example to drop out of its current persistent range. 
Chart: NZ vs. US 2-yr rates
The eroding of forward expectations for the RBNZ (NZ 2-yr rates have fallen some 50 basis points since late July and year forward rate expectations, according to a Credit Suisse index, have fallen some 65 bps over the same period. Some of the decoupling here between the NZDUSD's behavior and the rate spread has likely to do with China's interest in buying NZ assets. But looking back to February or so of this year on the chart, we can see that NZDUSD was trading below 0.75 at the current rate spread. 
If we get an upside break in risk appetite in the days ahead (US FOMC meeting will be a critical event risk across global markets next Wednesday and judging from recent action, the market is extremely twitchy on ad hoc Europe-related developments), then we are perhaps more likely to see a scenario in which we first build another "right shoulder" on the NZDUSD chart.

Daily Report: Euro Struggling to Extend Rally on Trichet, Kiwi Jumps Risk Appetite and Data

The risk on mode in financial markets continues as Asian equities are broadly higher following strong rally in US stocks overnight. New Zealand dollar leads the way after strong housing data which showed building permits jumped an impressive 13% mom in July. Australian and Canadian dollar closely follow. Swiss Franc continues to be the weakest currency as traders continue to reverse safe-have positions and on concern of more measures from SNB to curb franc strength, including the possibility of deposit charges. Dollar is soft in general but the loss against Euro and Sterling is so far limited and the dollar index is still holding above 73.42 near term support. Euro is still struggling to extend recent rally against dollar and sterling.

Euro bulls are somewhat disappointed by the soft comments from ECB Trichet. As he told in a testimony to the European Parliament, while inflation will likely remain above ECB's 2% target in near term, the bank is reviewing its medium term projections and outlook on inflation. Markets also noted that Trichet has dropped the language about "upside risks to p[rice stability". The new projections will be released in Septembers meeting and downside revisions there will reduce expectation of further hike from the bank. Euribor futures are already starting to price out further hike but starting to price in 30% chance of rate cut next year. We argued that ECB would keep rates unchanged through 2012. Technically, we're prefer to see EUR/USD taking out 1.46, EUR/GBP taking out 0.89 before confirming underlying strength.

FOMC minutes for the August 9 meeting will be the main focus of today. That's the meeting which Fed changed that language to " warrant exceptionally low levels for the federal funds rate at least through mid-2013", replacing "extended period" with a more explicit time frame. Three members dissented and preferred to continue to keep the "extended period language" which was used in the sixteen previous statements. The minutes to be released today should reveal the debate among policy members on such drastic change. Meanwhile, as Bernanke indicated last week, the September meeting will be prolonged by one delay to allow discussion of further easing from Fed. And today's minutes should give some hints on how hard it would be for Bernanke to convince other fellow policy members to vote for further stimulus measures, and what would those measures be.

On the data front, New Zealand building permits jumped 13% mom in July. Japan household spending dropped -2.1%yoy in July, retail trade rose 0.7% while unemployment rate rows to 4.7%. UK mortgage approvals, M4 money supply and Eurozone confidence indicators will be released in European session. Canadian current account, IPPI and RMPI, as well as US S&P Case-shiller house price and conference board consumer confidence will be released later in US session.

NZD/USD jumps further to as high as 0.8536 today so far and remains firm. However, note that the structure of the rebound from 0.7962 is looking corrective. First target of rebound at 61.8% projection of 0.7962 to 0.8410 from 0.8261 at 0.8538 is almost met. NZD/USD would possibly reverse between 0.8538 and 100% projection at 0.8709 to start another fall to extend the correction from 0.8842 high. Hence, we'll start to look for reversal signal on the next rise. Break of 0.8261 will turn outlook bearish for 0.7962 and below. 


EUR/GBP Daily Outlook

Daily Pivots: (S1) 0.8824; (P) 0.8851; (R1) 0.8870; 

EUR/GBP faced resistance from 0.8886 and retreated. With 4 hours MACD crossed below signal line, a temporary top is formed and intraday bias is turned neutral. After EUR/GBP continues to stay in range of 0.8642/8886 and near term outlook remains neutral. We'd prefer to see breakout on either side to confirm the outlook. On the upside, sustained break of 0.8886 will complete a head and shoulder bottom pattern (ls: 0.8704, h: 0.8642, rs: 0.8653) and confirm completion of decline from 0.9083 and should bring retest of this resistance. On the downside, below 0.8794 minor support should rule out the head and shoulder scenario and turn bias to the downside for 0.8642/53 support zone. Break there will resume whole fall from 0.9083.

In the bigger picture, price actions from 0.9799 (2008) should be unfolding as a consolidation pattern in the long term up trend. The first leg is completed with three waves down to 0.8067. At this point, EUR/GBP is still holding above 0.8610 support. Thus, there is no confirmation of completion of the second leg from 0.8067. Though, even in case of another rise, we'd expect strong resistance ahead of 0.9410 medium term resistance to bring reversal and starts the third leg. On the downside, break of 0.8610/42 support will now be an important bearish signal for 0.8067 and below.


Economic Indicators Update

GMT Ccy Events Actual Consensus Previous Revised
22:45 NZD Building Permits M/M Jul 13.00%
-1.40% -1.00%
23:30 JPY Household Spending Y/Y Jul -2.10% -3.50% -4.20%
23:30 JPY Unemployment Rate Jul 4.70% 4.60% 4.60%
23:50 JPY Retail Trade Y/Y Jul 0.70% 1.50% 1.10%
6:00 CHF UBS Consumption Indicator Jul

1.48
8:30 GBP Mortgage Approvals Jul
49K 48.4K
8:30 GBP M4 Money Supply M/M Jul
0.40% -0.50%
8:30 GBP M4 Money Supply Y/Y Jul

-0.70%
9:00 EUR Eurozone Consumer Confidence Aug
-16.6 -11.2
9:00 EUR Eurozone Economic Confidence Aug
102 103.2
9:00 EUR Eurozone Industrial Confidence Aug
-0.5 1.1
9:00 EUR Eurozone Services Confidence Aug

7.9
12:30 CAD Current Account (CAD) Q2
-13.6B -8.9B
12:30 CAD Industrial Product Price M/M Jul
0.00% -0.30%
12:30 CAD Raw Materials Price Index M/M Jul
0.00% -2.20%
13:00 USD S&P/Case-Shiller Composite-20 Y/Y Jun
-4.90% -4.50%
14:00 USD Consumer Confidence Aug
52.5 59.5
18:00 USD FOMC Minutes


Forex Technical Set-ups for the Week Ahead

Friday's movement should see EURUSD push towards 1.4700
Having moved higher off 1.4322 support on the weekly chart, EURUSD has clearly broken from the corrective channel (blue). An engulfing green candle from Friday should have the follow through to break through the triangle formation (pink), which should push the pair up towards 1.4700; the previous high; and 1.4746; the weekly trend line.
Bullish views of EURUSD could create long opportunities in GBPUSD
GBPUSD has pushed off 1.6289 support on the weekly. A large reversal candle was recorded on Friday, with the pair unable to hold below support. The pair has yet to make a higher low on shorter time frames.
However, the EURGBP chart (analysis to follow below) suggests a corrective pattern (lower), so with a EURUSD bullish view, pullbacks in GBPUSD might be seen as buying opportunities.

A choppy 3 wave corrective pullback could soon follow for EURGBP
On the weekly chart, EURGBP has recorded a bullish candle off support at 0.8691, however the previous area of resistance can be seen at 0.8880-0.8900.
On the daily chart, after producing a double bottom with divergence EURGBP has rallied strongly.
On the four hour chart, the 261.8% projection of the first wave would take the pair to 0.8894; close to the area of resistance, however the top may be in place from Friday’s 4hr engulfing pattern at the high. A corrective pullback is expected soon in a choppy three wave sequence. This might be seen as an opportunity to ‘get long,’ with the prime area being 0.8770 - 0.8750. A larger Bullish pattern is then likely to unfold with the resistance area (0.8900) broken to the upside.
Whilst views are bullish AUDUSD faces strong resistance at 1.0574
AUDUSD appears strongly bullish on the weekly chart. The pair does however face some some strong resistance at 1.0574.
On the daily chart, it looks like a higher correction is due in an ABC pattern. 1.0638; the 61.8% retracement; looks to be the first area of attraction.
A bullish triangle breakout (4hr engulfing candle) would suggest that the rally could extend past 61.8% with 1.0829 (78.6%) looking more likely.
Despite evidence of investor indecision, AUDJPY could move higher
The previous week produced an indecisive ‘Inside Doji’ in AUDJPY. Last week’s price action produced a bullish candle and; although still an inside candle; this gives the cross a slight upside bias.
Having now broken through resistance, AUDJPY looks set to make a larger bullish ABC correction. A perfect formation would see the pair target 83.50.
On the four hour chart, a bullish engulfing pattern should give the cross enough momentum to break and clear the high from the 17th August.
After consolidating, the DOW could move lower following the rally
Since the strong sell-off at the end of August the DOW has been consolidating in a large triangle formation. This consolidating pattern would normally have a slight bias to break to the downside, however Elliott Wave theory may see this as a 4th wave correction with wave C yet to be fully realised. The weekly candle also shows an Inside Harami candle, which illustrates indecision with a slight upward bias. This should only be a temporary rally before the next major sell off.
GBPJPY shows indecision, with Wave C targetting 127.75 to 128.00
For GBPJPY, the last two weekly candles have been inside the range of the week 8th August. This shows investor indecision at these levels.
The Daily chart suggest that a larger ABC formation has yet to complete with wave C targeting 127.75 - 128.00.
NZDUSD could target 0.8509 within an ABC corrective sequence
Price action in NZDUSD produced an engulfing green candle after the previous week's indecisive inside red.
The pair now looks set to produce a larger ABC corrective sequence with 0.8509 – 0.8612 the prime target area.
An ascending triangle breakout to the upside – trading with the bias could see the pair rally beyond the aforementioned area with 8840 the triangle target.
 

Daily Report: USD/JPY Bounces from Fresh Record Low on Intervention Fears

After hitting a fresh record low of 75.94 last Friday, the greenback finally rebounded this morning to a 1 ½ week high of 77.23 on active buying by an U.S. name (on behalf of a Japanese institutional investor), However, the currency pair ran into heavy offers by exporters and has retreated back around 76.70/75 due to lack of real action from Japanese officials. Although Ministry of Finance and even Japan's Prime Minister both came out and warned about the one-sided move in Japanese yen, as comments were pretty much the same as before, i.e. excessive Yen rise has a negative impact on the economy and the government is ready to take decisive action against any speculative and excessive moves if necessary, not much effect on the FX market, Finance Minister Noda added that it is too early to reach a conclusion on the BOJ/MOF intervention earlier this month (4 Aug), however, traders need something more solid in order to stop them from buying the Japanese yen. Over the weekend, a report from Nikkei business daily (Nikkei Shimbun) suggested that the Japanese government was considering intervention plus a comprehensive set of policy measures to stop the rise in yen which is dampening the nation's economy. The article indicated once Prime Minister Kan steps down, new measures will be implemented, studied easing measures include providing support to make high value-added product, expanding low interest loans to small and mid-size businesses and third supplementary budget. Another factor pushing the yen higher was risk aversion with weakness in global equity markets last Friday (Hang Seng and Nikkei 225 are still in red zone). Although some traders expect the USD/JPY to rally like the USD/CHF after the government announces new set of easing policy and intervenes the currency market again this week, if the intervention by BOJ/MOF remains unilateral, impact on the currency pair will still be short-lived. At the moment, bids from importers and U.S. banks are reported at 76.25-30 and 76.00 whilst offers from exporters remain from 77.00 all the way up to 77.50.

Although aussie rose in tandem with euro last Friday to a high of 1.0482, the currency pair met good selling by an Asian fund and pressured AUD/USD back to around today's low of 1.0363. Comments from Australian Treasurer Wayne Swan also seen undermining aussie as he said the high Australian dollar was placing tremendous pressure on trade exposed industries. Risk aversion led selling in AUD/JPY also drag aussie lower today with offers now reported in the region of 1.0440-60 (stops above 1.0475-85 and further out at 1.0520) whilst bids (also in AUD/NZD and AUD/JPY) from Japanese marginal traders, European names and real money investors are tipped at 1.0330 and 1.0300.

Against the European currencies, euro retreated from Friday's high of 1.4453 and locked in narrow range in part due to contradict comments from EU officials. ECB's governing member Nowotny was quoted in an Austrian magazine that he is fearing EMU states will not adopt EFSF revisions by end of October. On the other hand, German Finance Minister Schaeuble gave more upbeat remarks as he said the euro remains a stable currency and market correction on the downside has been exaggerated, there is no reason for lasting concerns. He also comments on German economy, indicating there is no sign of a recession and the country's labor market is very positive. This week's focus will be on peripheral yields in particular Greece, countries including Netherlands and Austria insisted on receiving collateral against their bailout loans. Once again the Swiss newspaper, SonntagsZeitung claimed that the Swiss government expects the Swiss National Bank to set the target for EUR/CHF peg at 1.2000 or above. The report also suggested that there are increasing pressure on SNB to take further action to weaken the Swiss franc.

Despite rising to a 3 1/s month high of 1.6618 last Friday (on the release of better-than-expected UK public finance data at -2.0 billion GBP), cable then retreated and gave back most of Friday's gain on speculation that Bank of England may expand the QEP. No data is due today with a light orders book, bids from UK clearer are reported at 1.6430-40 whilst offers are noted quite far at 1.6540-50.

USD/JPY Daily Outlook

Daily Pivots: (S1) 75.99; (P) 76.48; (R1) 77.02; 

The strong recovery today and break of 76.96 minor resistance indicates that a temporary low is formed at 75.94 and intraday bias is turned neutral. Some consolidations would be seen above 75.94 first and stronger recovery might be seen. But after all, we'll stay bearish as long as 80.23 and expect more downside ahead. Break of 75.94 will target 100% projection of 81.46 to 76.28 from 80.23 at 75.05 next.

In the bigger picture, USD/JPY is still staying well inside the falling channel that started back in 2007 at 124.13. There is no indication of trend reversal yet even though medium term downside momentum is diminishing with bullish convergence condition in weekly MACD. Such down trend is still in favor to continue to 70 psychological level. In any case, break of 80.23 resistance is first needed to indicate completion of fall from 85.51. Secondly, break of 85.51 is needed to be the first signal of medium term reversal. Otherwise, we'll stay cautiously bearish in the pair.

Weekly Review and Outlook Underlying Trends in Volatile Markets, Strength in CHF, AUD, NZD and JPY

We had a lot of noises in the markets recently. The US debt ceiling debate remained a major focus as the drama dragged on before the August 2 deadline. Moody's warned earlier in the month of a possible US downgrade. But the rating agency said in a statement on Friday that the triple A rating would likely be kept if the government could continue to pay bond-holders even if a deal can't be reached by the deadline. The Greece situation seems to be solved by markets' focus turned to Spain now as Moody's warned of a Spain downgrade. IMF also said in a report that outlook in Spain is "difficult" with risks "elevated" and the country is still in "danger zone". These noises triggered much volatilities in the markets but under these volatilities, there are trends.

And, the trends that really worth noting are, firstly Dollar, Euro and Sterling are staying in range against each other for the moment. Dollar is a bit weaker against the other two. Sterling also seems to be building momentum against euro. But, they're kept in range as each region has its own problems. Growth in US and UK was dismal. US real GDP grew at 1.3% annualized pace in Q2, substantially below market expectation of 1.7%. Prior quarters figure was also revised down from 1.9% to a very poor 0.4%. UK Q2 GDP grew a mere 0.2% qoq. Outlook in both US and UK reflect fragility in economic recovery and would likely prompt Fed and BoE to add stimulus if situation worsens. Eurozone CPI unexpectedly moderated to 2.5% yoy in July, reducing the need for ECB to continue tightening while the region is still in the middle of the never-ending peripheral debt crisis. The trends between the three currencies are indeed, not too clear.

Secondly, Swiss France and Gold are both strong on safe haven demand. Swiss franc extended the long term up trend and made new record high against Dollar, Euro, and Sterling last week. Gold also jumped to record high against Dollar at 1637. Investors are still in deep concern on the debt problems across the Atlantic. Swiss Franc and gold would likely remain strong in near term ahead.

Thirdly, with all the talk about US downgrade, long term treasuries were still strong. Considering sluggish growth, risk aversion as well as possible reversal in stocks, US treasuries remained one of the preferred place for funds. Yield on 10 year and 30 year bonds both hit fresh low for the year last week. The strength in US bonds, weakness in yields, helped drive USD/JPY lower last week, taking EUR/JPY and GBP/JPY with it. The medium term down trend in yields are confirmed and we'd possibly see 10 year yield heading back to lower side of the range near to 2.35% while 30 year yield would possibly head towards 3.50% level Such development will likely support the Japanese yen further.

Fourthly, Aussie and Kiwi are both strong in spite of risk aversion in the equity markets, both supported by resilience in their economy, strength in the Asia Pacific region as well as commodity prices. The stronger than expected Q2 CPI reading in Australia killed unjustified talk of rate cut from RBA. Instead, markets are back to consensus that the bank would indeed be forced to raise rate again by the end of the year and such expectations boosted Aussie to new record high against dollar. In the post meeting statement, RBNZ delivered clearly the attention to remove the post-earthquake 50 bps insurance cut as 'current global financial risks recede and the economy continues to recover'. It's very likely that the rate hike will place in as soon as September.While also a commodity currency, trend in Canadian dollar is not clear, in particular as weak data cooled speculation of BoC hike in near term.

So in short, we're not too enthusiastic on trades in EUR/USD, GBP/USD and EUR/GBP. Instead, we'd be more interested in going long Swiss Franc and Yen on days of risk-off, and long on Aussie and Kiwi on days of risk-on.

Technical Highlights
GBP/CHF's long term down rend resumed last week and dived to new record low of 1.2880. Current fall should continue in near term and target 161.8% projection of 1.5691 to 1.4168 from 1.5183 at 1.2719 next. 
In the larger picture, we'll stay bearish as long as July's high of 1.3697 holds and expect the down trend to continue to 61.8% projection of 2.4965 to 1.5112 from 1.8113 at 1.2024 in medium term, which is close to 1.2 psychological level. 

NZD/USD's up trend accelerated further last week and made new record high at 0.8797 so far. We're staying bullish in the pair and expect the up trend to extend to 100% projection of 0.4890 to 0.7632 from 0.6560 at 0.9302 in medium term. Key short term support is last week's low of 0.8611 while the medium term key support level is 0.7975. 
Canadian dollar is clearly the weaker one among commodity currencies. AUD/CAD's strong rally last week suggests that pull back from 1.0555 has already finished at 1.0124. Current rise should extend through 1.0555 high in near term to target 61.8% projection of 0.9605 to 1.0555 from 1.0124 at 1.0711. 
In the larger picture, we'll stay bullish in AUD/CAD as long as 1.0124 holds and expect further rise to 100% projection of 0.7168 to 0.9913 from 0.8589 at 1.1333. 
The sharp fall in 10 year yield on Friday took out 2.847 support to close at new yearly low of 2.805. The fall might indeed be reaccelerating based on current structure. 2.688 Fibonacci projection will be a key level to watch in near term and a decisive break there will indeed suggest further downside acceleration ahead for a test on lower side of the medium term range near to 2.334. 
Dollar index attempted for a recovery last week but was limited by near term trend line turned resistance. No change in the outlook that consolidation pattern from 72.69 has finished at 76.71. We'll stay bearish in the index as long as 55 days EMA (now at 74.83) holds and expect an eventual break of 72.69 support to extend the down trend from 88.70. Nevertheless, note again that the outlook in EUR/USD is not cleared yet. And, a break of 55 days EMA in the dollar index will also mix up its outlook too. 

The Week Ahead
US debt ceiling outcome will be one of the major focuses on early part of the week. Four central banks will meet this week, RBA, ECB, BoE and BoJ and all are expected to stand pat. The main market moving one would be RBA and the statement could send Aussie further higher if it delivers a hawkish tone. Meanwhile a number of economic data would be released during the week.
As noted before, firstly Euro, Sterling and Dollar are so far kept in range against each other and the development among these crosses will very much depends on the PMIs and US job data. Also, these data would be important to determine the level of risk aversions and thus determine whether Swiss Franc or Aussie/Kiwi are the preferred currency to go long against dollar, euro and sterling. There are also a number of important data to determine how far the Aussie could go, including Australia retail sales, housing, trade balance and more importantly, China manufacturing PMI. New Zealand dollar bulls will look into New Zealand job data too. Meanwhile, also note that Canadian job data is also featured which could trigger some volatility in CAD crosses even though we don't expect it to change the larger trend.
  • Monday: China Manufacturing PMI; Eurozone manufacturing PMI, unemployment rate; UK manufacturing PMI; US ISM manufacturing
  • Tuesday: RBA rate decision, Australia building approvals, house price index; Swiss retail sales, SVME PMI; UK construction PMI; Eurozone PPI; US personal income and spending
  • Wednesday: Australia retail sales, trade balance; Eurozone services PMI final, retail sales; UK services PMI; US ISM non-manufacturing, factory orders; New Zealand employment
  • Thursday: BoE rate decision; ECB rate decision; US jobless claims
  • Friday: RBA monetary policy statement; BoJ rate decision; Swiss CPI; UK PPI; Canadian employment, building permits, Ivey PMI; US non-farm payroll

Weekly Review and Outlook: Eurozone Dominated Headlines but Kiwi and Aussie Shone; Important Week ahead, Dollar Vulnerable

Eurozone debt crisis dominated headlines last week and the highly anticipated EU summit delivered new measures to fund Greece and stabilize the situation. The results gave the common currency a strong boost towards the end of the week but Euro is so far limited below near term resistance level against dollar, yen and swissy and thus, there is no confirmation of a return to confidence. Improved risk sentiments, though, helped commodity currencies rally across the board together with strength in equities. New Zealand dollar and Australian dollar were both strong while Canadian dollar pared much of the earlier gains on weak inflation data. The greenback was broadly lower except versus swiss franc and dollar index's breach of 74 level suggested more downside to come ahead. 

The EU summit ended with new measures to fund Greece and stabilize the sovereign crisis in the Eurozone as a whole. he leaders also agreed on an ambitious reform of the EFSF, making it more flexible and effective. However, markets were somewhat disappointed with the lack of details on reform of the EFSF. The new bailout package for Greece by EU/IMF will total EUR 109B. Involvement in private sector will be on a 'voluntary basis' and the total contribution will be around EUR 50B (the net contribution of EUR 37B and EUR 12.6B from a debt buy back program). The document stressed that the private sector involvement arrangement is an 'exceptional and unique solution' for Greece only. Interest rates are lowered to 3.5%. Maturity of the loan, as well as other loans from the EFSF in the future, will be extended 'from the current 7.5 years to a minimum of 15 years and up to 30 years with a grace period of 10 years'. Rate reduction and maturity extension should also benefit Portugal and Ireland on their current debts, too. Greece is required to accelerate implementation of fiscal consolidation measures including privatization of Government assets worth of EUR 50B. The leaders also reached a common position to enhance the importance of ESFS, giving it the ability to buy Eurozone debts in secondary markets. This, however, can only be done upon approval of the ECB and under 'mutual agreement' of the EFSF/ESM member countries. The fund can also give countries 'precautionary' credit lines and recapitalize financial institutions through loans.

In the US, hopes that the White House and the Republicans would reach an agreement soon faded after the news that Obama met with Democratic leaders from the House and Senate at the White House for about two hours as some of them rejected the plan proposed by the 'Gang of Six' on July 19, aiming to cut spending by 3.75 trillion over 10 years. House Speaker John Boehner said after Friday market close that he will instead talk with Senate leaders on a way to avoid a U.S. default. Meanwhile, S&P issued a new warning that it would downgrade US' credit rating if a deal failed to be reached by August 2. The rating agency said there's at least 50% chance that it would cut the country's AAA rating for the first time.

BOC left interest rate unchanged at 1% in July. GDP growth forecast was revised to +2.8% for 2011, down from +2.9% projected in April, while estimates for 2012 and 2013 stayed unchanged at +2.6% and +2.1% respectively. Policymakers saw higher inflationary pressures with core inflation slightly firmer than expected, due to 'temporary factors' and 'more persistent strength in the prices of some services'. Core CPI is expected to 'remain around 2%' through 2013 while total CPI should return to the 2% by the middle of 2012. Concerning monetary policy outlook, the BOC concluded that 'to the extent that the expansion continues and the current material excess supply in the economy is gradually absorbed, some of the considerable monetary policy stimulus currently in place will be withdrawn'. The reference this month, with the term 'eventually' being taken away, sent the market a signal that a rate hike may come earlier than previously anticipated. Canadian dollar surged after the statement but later pared much of the gains on Friday as CPI dropped more than expected to 3.1% yoy in June. while core CPI also unexpectedly moderated to 1.3% yoy. 

Australian dollar and New Zealand dollar were the two biggest winners last week and fear on European debt crisis eased and risk appetites came back. The Aussie lagged behind other commodity currencies in July on talk that RBA might cut rates in the next twelve months. But the idea, as proposed by Westpac, didn't gain many followers and the Aussie jumped as Gold reached new record high above 1600, as well as on strength in global equities. New Zealand dollar was even stronger as Q2 CPI accelerated more than expected to 5.3% yoy, highest number since 1990. Along with the better than expected GDP figure released a week ago, markets are now expecting RBNZ to start tightening again in Q4. 

Technical Highlights

Dollar index's break of 74.13 support suggests that rise from 73.35 has finished at 76.71. Also, the consolidation pattern from 72.69 might be completed with three waves up to 76.71 too. Bias is cautiously bearish this week for a test on 73.50 support. Break there will affirm the case the the down trend in dollar index from 88.70 is resuming for another low below 72.69. Ideally, that should be accompanied by a break of 1.4577 in EUR/USD. 

NZD/USD is one of the strongest pair in July so far and made another record high of 0.8674 last week. There is no sign of topping yet and the pair is indeed accelerating. We're staying bullish and expect further rally ahead. From a medium term angle, NZD/USD should be targeting 100% projection of 0.4890 to 0.7632 from 0.6560 at 0.9302 next. 

The Week Ahead

Talk on US debt ceiling will be a main focus this week. An agreement must be made to raise the current $14.3T borrowing limit by August to avert a default. Meanwhile, a number of key economic data will be released this week. From US and UK, Q2 GDP preliminary reading will be the major focus. Canadian dollar will also need a strong GDP number affirm the expectation of BoC hike in H2 and fuel another rally. Meanwhile, Q2 inflation data from Australia will also be crucial on whether RBA's next move would be a hike or as some said, a cut. RBNZ is expected to leave rates unchanged at 2.50% this week but may start to hint on tightening in H2 and thus, give the New Zealand dollar further boost. 

Meanwhile, a key focus of the week will also be on whether US stocks could extend recent rally. So far, DOW is still limited below May's high of 12876 but it's looking increasingly likely that rise from 11862 is resuming the medium term up trend. We'd expect any retreat to be contained above last week's low of 12296 and DOW should break through 13000 level, maybe after agreement on US debt ceiling and deficit reduction, or after Q2 GDP data. Such development, if happens, will give much pressure on the dollar. 

 AUD/USD Weekly Outlook

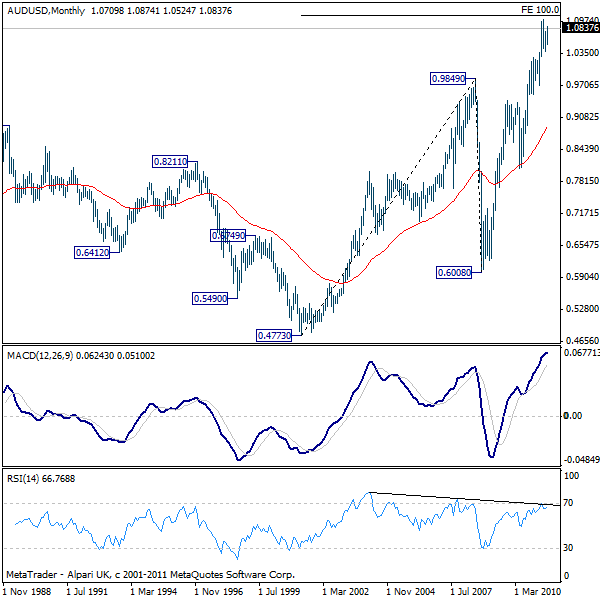
AUD/USD broke out of near term range last week and rose to as high as 1.0874. Rise from 1.0390 has resumed and should be target a test on 1.1011 resistance this week. Overall outlook remain unchanged. we're still favoring the case that correction pattern from 1.1011 is finished with three waves down to 1.0390 already and rise from there is tentatively treated as up trend resumption. Break of 1.1011 will confirm and target 61.8% projection 0.9703 to 1.1011 at 1.0390 at 1.1198 next. On the downside, below 1.0774 minor support will turn bias neutral and bring consolidations first. But downside should be contained well above 1.0524 support and bring another rise.

In the bigger picture, rise from 0.8066 is part of the up trend from 2008 low of 0.6008 and is still in healthy status. Such up trend should target 100% projection of 0.6008 to 0.9404 from 0.8066 at 1.1462 on resumption. On the downside, Break of 1.0182 resistance turned support is needed to be the first signal of medium term reversal. Or we'll stay bullish in AUD/USD.

In the longer term picture, long term up trend from 0.4773 (01 low) is still in progress and would possibly target 100% projection of 0.4773 to 0.9849 from 0.6008 at 1.1084. AUD/USD is staring to show loss of upside momentum with weekly MACD crossed below signal line and there is possibility of bearish divergence condition too. Nevertheless we'd still prefer to see at least sustained trading below 55 weeks EMA (now at 1.0055) before considering long term reversal. 
 

Risk back in favour?

After an incredibly dull day yesterday with the major markets closed, it was Asia again that led the charge, risk seemingly back in favour this morning as I walk in, on the back of what seems a relatively innocuous Wall Street Journal article citing the fact that Germany is prepared drop its push for restructuring of the Greek debt in an effort to facilitate a new aid package for the beleaguered southern nation. Coupled with the fact that the EURUSD was trading above that 1.4250 pivot level at the time that the market took notice of this article was enough to push the cross through stops in a hunting frenzy and allow it to trade at a  high of 1.4405 or thereabouts overnight. In other news we see the NZDUSD trading at all time highs as consumer and business confidence registered its biggest print in over a year, all the while the rather confused finance minister was off jawboning and contradicting himself yet again.

Adding to the excitement was Moody’s out saying that it would place Japan on review for a possible downgrade.
Turning to the day ahead, we all know it’s month end and some of the flows we’ll see today are clearly going to be related to this, meaning more USD sales if anything. Beyond this we have the Bank of China interest rate announcement as well as the Eurozone flash CPI estimate printed this morning.
With regard to the market, looking at the EURUSD first, given the current price action, equities and commodities all higher it’s hard to imagine that the pair won’t test (and in all likelihood take out) resistance sitting at the 1.4430 area. After a brief stop run above there I would expect the cross to settle into a 1.4300/1.4400 day.
The Cable is benefiting once again from broad USD sales and looks for 1.6580 as the next natural cap. If this sentiment persists for the bulk of the day it’s not unlikely to see the cross trading into serious offers sitting around the 1.6650 area.
The AUDUSD traded higher on the back of all of the above taking out stops above 1.0730 and trading to 1.0750 on the exhaustion that followed. Fading rallies intraday might be the way forward with sales and stops needing to go in closer to that overnight high area.
The JPY and its crosses are understandably a little battered on the back of this briefly renewed risk sentiment and Moody’s news, however they remain confined for the most part. EURJPY is the current standout for being overdone on this spike and selling at market is the call amongst a few of my contacts with their stops going in above 118.30, looking for a return to around the mid 115 area.
CHF data this morning proved to be worse on both the headline and the devilish detail but the only cross getting anything out of this was the EURCHF which has spiked but still trades heavy nonetheless.


Daily Report: Dollar Broadly Lower, Swiss Makes Record Highs

The economic data triggered selloff in dollar extends further today, sending the greenback broadly lower. Overnight comments from EU Juncker triggered brief pull back in EUR/USD but that was quickly overshadowed by weakness in the greenback. Drop in treasury yield is also seen as another factor weighing on the dollar as 10 year yield drops to a six-month low over night. Swiss franc jumped to new record high against dollar and euro as IMF urged SNB to raise rates. Meanwhile, Kiwi extends recent rally to a three year high, taking the Aussie higher too.
The rally is Swiss franc is particularly impressive. Safe haven flow from Euro is once factor which IMF's comments added more fuel. The IMF noted that Switzerland's exception fiscal position of nearly balanced budget and said "with the output gap closing and a below neutral policy interest rate, monetary accommodation should be withdrawn in the near-term under the baseline scenario."
There was temporary setback in EUR/USD's rebound over night after President of Eurogroup of finance ministers Juncker said Greece won't reach its 2011 budget deficit goal, and that the IMF may withhold the next tranche of Greece's bailout funds. Also, former ECB economist Issing accused that Greece "cheated" to get in Eurozone. The comments kept Euro under pressure in crosses.
On the data front, Japan core CPI rose 0.6% yoy in April, first rise in two years on a spike in energy and tobacco prices, retail sales dropped -4.8% yoy in April. UK Gfk consumer sentiment improved to -21 in May. Eurozone M3 and confidence indicators will be released. Swiss KOF leading indicator will be a focus as Swiss bulls would draw every excuse to send the currency higher. From US, personal income and spending will be released and dollar selloff might extend further in case of data disappointment.
New Zealand dollar has been exceptionally strong this week. NZD/USD's break of 0.8118 resistance yesterday confirms up trend resumption. And that's supported by rising upside momentum too. 0.8213 record high set in 2008 should be taken out in near term with ease and we're expecting the uptrend to extend further to 100% projection of 0.6559 to 0.7973 from 0.7115 at 0.8529 in medium term. 

Meanwhile Swiss Franc also rose to new record high against sterling overnight. GBP/CHF dropped to as low as 1.4028 so far. Current down trend should now extend through 1.4 psychological level to 100% projection of 1.5689 to 1.4295 from 1.5169 at 1.3775 next. 

FX Update: NZDUSD bearish below 0.7945

We're finally seeing a bit of a correction developing in the torrid upside in the commodity currencies, though the development has been rather shallow relative to the usual warning indicators on these trades from intermarket action. The correction in equities, strength in the Japanese yen of late and strength in the bond markets suggest that the likes of NZD may have a bit of catching up to do on the downside.
Considering the relatively strong rejection of the overnight high at 0.7950 in NZDUSD, the market may look to test the downside and the mettle of the bulls. As long as the pair trades below 0.7945, the tactical outlook for NZDUSD is bearish, while the pair may be ready for a run down to an objective of 0.7775 initially and then on to 0.7660 for a second objective. Of course, the risk to such an outlook here is that the timing is off and it is a lost cause to fight such a steep uptrend until we've seen a larger scale sell-off develop.

FX Update: Euro traders wearing rose-coloured glasses?

The challenges to the Euro seem to be mounting from the sovereign debt and potential banking system contagion perspective, but the market continues to merrily snap up the Euro on the latest hawkish chatter from the ECB and a fresh high in the CPI today. Can the single currency continue to defy gravity?
The fence around the PIGs?
Euro traders have apparently built quite the PIG-wire fence around the situation in Portugal, Ireland and Greece. As the situation in these three countries sees little improvement in terms of moving toward a resolution of their sovereign debt issues and Portugal teeters toward a default, traders seem to be shrugging their shoulders and only focusing on the latest wrinkle in the ECB rate outlook and probably also today’s CPI estimate for March. We’ve had a number of ECB officials out yesterday and today talking up the higher course for ECB rates in coming months and next Thursday’s hike appears to be a done deal. The year-forward expectations are now pushing 126 bps, according to a Credit Suisse index of central bank expectations. By comparison, Fed expectations are at around 45 bps.
For those of us a bit more worried about the risk of contagion from the PIGs and into the European banking system, there is this Bloomberg article to consider on whether an Irish bond haircut could risk shutting funding for Italy and Spain. This risk is nowhere near being priced into the Euro, as the market still assumes that the situation will somehow resolve itself well – judging from the action in EURUSD, EURGBP and EURJPY.
Today, the Irish bank stress tests will see the release of the capital amounts needed to prop up the Irish banks (expectations running around EUR 20 billion). Some estimates of what the bailout for Ireland will cost taxpayers run into the EUR 65 billion range. On a per capita basis, that would be like the U.S. taxpayer being forced to bailout U.S. banks to the tune of about USD 5 trillion. It is a patent absurdity. Our question for the longer term: why, why, why does Ireland want to keep the Euro? The only way it will do so in the longer run is if it restructures this now national debt that stems from these banks’ bad loans from the bubble days. And the restructuring will need to be more than a haircut – more like a removal of the head and torso as well.
Fed talk
The market shrugged off follow-up comments from the St. Louis Fed’s Bullard late yesterday, who suggested again (after Saturday comments) that ending QE2 ahead of time should be considered, and might be viewed as an “important signal” rather than making any large impact in the market. The outgoing (in October, he is also a non-voter) KC Fed president Hoenig burnished his hawkish reputation by lambasting current Fed policy and partially blaming it on the world’s commodity price spike and the risk of aggravating new bubbles. He said the natural U.S. rate was two percent. It appears we need to see the Fed chairman himself talk the hawkish talk before we see the market tip its hat at the credibility of the Fed and the USD.
Odds and ends
U.K. GfK Consumer Confidence remained at last month’s level at -28 rather than seeing an expected further decline to new recent lows. The Nationwide survey showed March confidence at the lowest level since the beginning of the survey in 2004, while the older GfK survey saw its lowest reading in July of 2008 at -39.
The Japanese manufacturing PMI out overnight is the first hard evidence of how the tsunami/earthquake has knocked the Japanese economy for a loop. The numbers for April are likely to be worse, unfortunately. And the impact of further evacuations on radiation concerns suggest that the disruption could still be spreading.
The data out of Australia overnight showed Retail Sales slightly stronger than expected and Building Approvals down sharply. Both can be contributed to the after-effects of devastating floods from earlier this year, as the areas of the floods saw the sharpest declines in approvals. Still, the data was far worse than expected and the drop in activity is a strong forward indicator that the Australian housing bubble is in danger of unwinding soon.
Please follow this “copper in China as loan collateral” story that ftalphaville has covered on a number of occasions recently, including in a piece today. This shows how unusual the Chinese banking system is and in particularly, how some key commodity prices are possibly being propped up by this “system”. The implications for Aussie volatility are rather clear if this system ever breaks down, so a long volatility card or two in the pocket might be  reasonable.
U.S. Jobless Claims were out “at 6k lower than last week”, but that headline doesn’t show that the 388k number was worse than the 380k expected and that last week’s number was revised sharply up from an original 382k to a revised 394k – so it’s actually a relatively negative data release.
The spiking NZD looks like a result of capital flows from the earthquake rather than any recovery in fundamentals. Consider the drop in the Business Confidence survey in March from 34.5 to -8.7. NZDUSD is on a tear that it can hardly sustain for much longer, but a technical reversal is so far nowhere to be found. One on the way today or tomorrow?
Looking ahead
Our broken record warning for the day is that this is the end of the month/quarter/Japanese financial year and that anything can happen. Also watch out for the release of the stress tests for the Irish banks and the situation in Portugal – which is teetering rapidly toward its own bailout. Tomorrow we have the U.S. employment report and the G20 (likely only a Euro-debt/Japan focus there) this weekend.
In the meantime, just as we are about to go to press, oil and gasoline prices are spiking higher out of the range of the last several days, possibly on news out of the Middle East. Is this really time to leverage up on the risk trades? We have to imagine that the risk bulls are a bit over-extended here now that we have come full circle in risk markets from the catastrophe in Japan.
Be careful out there.

Economic Data Highlights
UK Mar. GfK Consumer Confidence out at -28 vs. -30 expected and -28 in Feb.
UK Mar. Hometrack Housing Survey out at -0.1% MoM and -3.2% YoY vs. -2.7% YoY in Feb.
Japan Mar. Nomura/JMMA Manufacturing PMI out at 46.4 vs. 52.9 in Feb.
Australia Feb. RP Data-Rismakr House Price Index out at 0.0% MoM
Australia Feb. Retail Sales out at +0.5% MoM vs. +0.4% expected
Australia Feb. Building Approvals out at -7.4% MoM and -21.8% YoY vs. +4.0%
New Zealand Mar. Business Confidence fell to -8.7 from 34.5 in Feb.
Japan Feb. Housing Starts out at +10.1% YoY vs. +7.4% expected and +2.7% in Jan.
Germany Feb. Retail Sales out at -0.3% MoM and +1.1% YoY vs. +0.4%/+1.5% expected, respectively and vs. +2.6% YoY in Jan.
UK Mar. Nationwide House Prices out at +0.5% MoM and +0.1% YoY vs. 0.0%/-0.6% expected, respectively and vs. -0.1% YoY in Feb.
Germany Mar. Unemployment Change out at -55k vs. -25k expected
Germany Mar. Unemployment Rate out at 7.1% vs. 7.2% expected and 7.3% in Feb.
Norway Feb. Retail Sales out at +0.7% MoM and +2.7% YoY vs. +0.5%/+1.3% expected, respectively and vs. +0.4% YoY in Jan.
EuroZone Mar. CPI estimate out at +2.6% YoY vs. +2.4% expected and vs. +2.4% in Feb.
Canada Jan. GDP out at +0.5% MoM and +3.3% YoY vs. +0.5%/+3.1% expected, respectively and vs. +3.3% YoY in Dec.
US Weekly Initial Jobless Claims out at 388k vs. 380k expected and vs. 394k last week
US Weekly Continuing Claims out at 3714k vs. 3705k expected and 3765k last week

Upcoming Economic Calendar Highlights (all times GMT)
US Mar. Chicago PMI (1345)
US Weekly Bloomberg Consumer Comfort Index (1345)
US Mar. NAPM-Milwaukee (1400)
US Feb. Factory Orders (1400)
US Fed’s Lacker to Speak (1430)
US Fed’s Tarullo to Speak (1645)
US Fed’s Pianalto to Speak (1805)
New Zealand Q4 Manufacturing Activity (2145)
Australia Mar. AiG Perfomance of Manufacturing (2230)
Japan Q1 Tankan Large Manufacturer’s Index (2350)
China Mar. PMI Manufacturing (0100)
China Mar. HSBC PMI Manufacturing (0230)

Ratings and Recommendations